fomo

Screenshots
Details
- Rating
- 122.00 reviews
- Version
- 1.87.1
- Developer
- fomo Labs Inc.
Analysis by Norviv
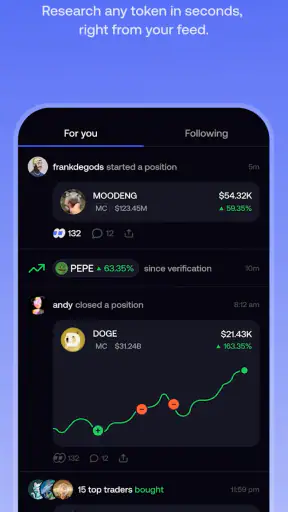
I tried fomo as a finance app with a social angle, and my first impression was that it is aimed at people who do not want to discover every market idea alone. Instead of treating investing as a completely private activity, it puts attention on what friends and other people are following. That can make the experience feel more approachable, especially if a financial app normally seems dry or difficult to navigate.
The important distinction is that fomo is not simply a replacement for a bank app or a conventional portfolio tracker. Its identity is built around social discovery and timing. I found that useful when I wanted to compare my own curiosity with what people around me were watching, but it also created a responsibility: seeing a trend is not the same as understanding it. The app can help start a conversation, yet it should not make the decision for you.
It is available as a free finance app from fomo Labs Inc., with an Everyone content rating. The current release is version 1.87.1, and it requires an operating system version 9 or later. Those details make it accessible for many everyday phones, including a device that may be shared around a household, although the way people use a shared device deserves more thought than the simple installation process.
How fomo fits into a shared household
A realistic use case is a couple or group of housemates who regularly talk about money, technology, companies, or market trends. One person may notice an interesting movement through the app, while another asks why it matters before taking any action. In that setting, fomo works best as a conversation starter. It gives the household a common place to look at ideas rather than relying on scattered messages and screenshots.
I would not treat that shared-device scenario as permission to merge everyone’s financial identity. A finance app should be approached with clear personal boundaries, even when the phone belongs to the household. Each person needs to know which account they are using, whose opinions they are following, and whether an action reflects their own judgment. Social visibility can be useful, but it should never be confused with shared ownership or shared responsibility.
That distinction matters because the app’s appeal comes from following people and trends. If several household members use one phone, a quick handoff can easily blur who was browsing and who was making a decision. I recommend agreeing on a simple habit: identify the active user before exploring, avoid leaving a session open for someone else, and discuss ideas separately from any personal financial action. These are ordinary precautions, but they make the social side much safer and less confusing.
For a family with teenagers, I would keep the experience firmly educational and supervised. The Everyone rating describes the app’s age classification, not a promise that every financial decision is suitable for a child. A young user may understand how to follow a trend long before understanding risk, loss, concentration, or the difference between popularity and evidence. I would use fomo to discuss how people form opinions, not as a shortcut to independent investing.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
Setting boundaries before the first session
The setup conversation is more important than it may seem. Before anyone starts following friends, decide whether the app is being used for general observation, personal research, or active financial decisions. Those are three different jobs. For observation, the main concern is privacy and clarity. For research, the main concern is checking information elsewhere. For action, the main concern is whether the user understands the consequences and has a suitable account or service for that action.
I also suggest separating “interesting” from “urgent.” The social design can make a popular idea feel time-sensitive, particularly when several people appear to be paying attention at once. My practical rule is to record why an idea caught my attention, then wait until I can explain it without referring to the crowd. If I cannot describe the underlying reason in plain language, I am not ready to treat it as a serious decision.
Another useful boundary is personal versus household money. A shared phone does not make a shared budget, and a friend’s activity does not create an obligation to copy it. Couples can discuss broad goals, such as saving or learning, while keeping individual choices distinct. That approach preserves the social benefit without turning the app into a source of pressure.
Because fomo is free, the barrier to trying it is low. That is convenient, but it can also encourage casual installation without a plan for how it will be used. I would start with a limited purpose: follow a small circle of relevant people, observe how the feed affects your attention, and decide whether the experience improves your research. If it mainly creates anxiety or makes every trend feel like a missed opportunity, that is a sign to reduce usage rather than chase the feeling.
Coordination without copying
The strongest household use I found is coordinated learning. One person can bring an idea to the table, another can challenge the reasoning, and a third can look for information outside the app. This turns social discovery into a small review process. The app supplies the starting point, while the household supplies the questions that a trend feed cannot answer by itself.
A simple workflow is helpful. First, note what attracted attention: a person, a topic, a sudden change, or a broader theme. Next, ask what would make the idea wrong. Then check whether the interest is based on a short-lived reaction or a reason that still makes sense after some time. Finally, decide whether the idea belongs in a watch list, a research note, or nowhere at all. This prevents the most visible item from automatically becoming the most important one.
That workflow also makes fomo more useful for friends who do not have the same level of financial knowledge. Rather than telling someone to follow a popular idea, I would ask them to explain what they think they are seeing. If they cannot identify the risk or the reason for the trend, the next step should be learning, not acting. In my view, this is where the app can support better habits: it makes discussion easy, but the discussion still needs discipline.
There is a trade-off here. Traditional finance apps often feel calmer because they focus on balances, transactions, charts, or private research. fomo is more engaging when the user wants discovery and social context, but that same energy can distract from a long-term plan. If your main need is budgeting, bill management, tax preparation, or a quiet record of holdings, a conventional finance tool is likely the better fit. I would use fomo alongside those tools, not assume it can replace them.
Another limitation is that social signals can be difficult to interpret. A person may follow a trend for curiosity, research, entertainment, or a completely different time horizon. The app’s social context does not automatically reveal the reasoning behind someone’s interest. I would therefore treat every visible signal as a prompt for questions, not as a recommendation. That is especially important in a shared household, where one person’s confidence can influence everyone else.
Trust, age, and personal responsibility
fomo’s Everyone rating makes it suitable for a broad audience from a content-classification perspective, but financial maturity is a separate issue. I would be comfortable introducing the app to an adult who can distinguish social activity from financial advice. For younger users, I would keep the account and discussion within an adult-led learning context and avoid presenting popular activity as proof that an action is sensible.
Trust also applies to friends. Following someone does not mean knowing their goals, income, risk tolerance, or reasons for paying attention to a particular trend. Even close friends may be experimenting, speculating, or simply browsing. I found it healthier to ask, “What are you trying to learn from this?” rather than, “Should I do the same thing?” That small change keeps the relationship supportive without making one person responsible for another person’s money.
On a shared device, trust includes practical privacy. I would avoid assuming that a partner, child, or housemate should automatically see every financial interest or browsing choice. If the device passes between people, signing out when appropriate and keeping conversations explicit are sensible habits. I am not treating those steps as special fomo features; they are user-side boundaries that matter whenever a finance app is used by more than one person.
The app’s popularity suggests that the social approach resonates with many users. It has an average rating of 4.8 from around 2.8 thousand ratings, and it has passed 500 thousand installs. I see those figures as evidence that the concept is connecting with a substantial audience, not as proof that the app will suit every financial personality. A high rating cannot remove the need to question trends, and a large user base cannot turn social attention into certainty.
I also appreciate that the product is focused enough to be easy to explain: find people and trends that interest you, then use that information to guide your own research. The drawback is that a focused social purpose may feel narrow if you expect a full financial dashboard. Users looking for detailed household budgeting, comprehensive account administration, or a complete planning system should compare it with tools designed specifically for those tasks.
Everyday use and practical limits
Imagine checking the app during a lunch break because a friend mentions an emerging topic in a group chat. I would open fomo to understand what has attracted attention, save the name or idea in my notes, and close the app before making any decision. Later, I would return with a clearer question and compare the idea with information from a more traditional source. That sequence keeps the app in its strongest role: discovery first, judgment later.
For a household, an evening discussion could follow the same pattern. One person shows what they found, another asks what evidence supports it, and everyone agrees that no one is expected to participate. This is a better use than passing the phone around and treating the most exciting item as a group project. It also protects relationships, because disagreement remains about an idea rather than turning into criticism of someone’s financial choices.
The main friction I experienced with this kind of app is psychological rather than technical. Social feeds naturally reward attention, and finance adds real consequences to that attention. A user who already worries about missing opportunities may find the experience stimulating at first and exhausting later. I would set a time limit for browsing and avoid checking whenever I am tired, rushed, or looking for reassurance after a market move.
I would also skip fomo if you want completely private, self-directed research with no social influence. A spreadsheet, a conventional portfolio tool, or a trusted research service may suit you better. Likewise, if you are searching for a budgeting app that organizes household bills and spending, this is not the category I would choose. Its value is the connection between people, ideas, and early awareness, not the management of every part of personal finance.
The developer, fomo Labs Inc., has kept the product’s identity clear enough that I never confused it with a general-purpose banking utility. That clarity is helpful when expectations are realistic. I would install it for a social lens on finance, then keep a separate method for checking facts, setting goals, and recording decisions. The app becomes more useful when it has a defined place in that larger routine.
My household verdict
After using fomo, I see it as a good fit for adults who enjoy discussing financial ideas and want to notice what their friends or wider community are watching. It can make research feel less isolated and can give a household a shared vocabulary for talking about trends. The best results come when users remain curious but skeptical, treating the feed as a starting point rather than a command.
For shared-device use, I would recommend clear account boundaries, separate decision-making, and an explicit agreement that nobody has to copy anybody else. Families can use it to teach questions about evidence and risk, but the Everyone rating should not be mistaken for a guarantee that children are ready to make financial choices. Adults should remain responsible for the context and the consequences.
My final recommendation is positive but specific. Try fomo if you want social discovery in a finance app and are willing to slow down before acting. Keep a traditional tool for budgeting or portfolio administration, verify ideas outside the social feed, and notice whether the experience improves your judgment or merely increases your fear of missing out. Its real strength is turning financial curiosity into conversation, while its real weakness is making attention feel more urgent than understanding.
With that balance in mind, I can recommend fomo to thoughtful adult users, couples who communicate well about money, and households that treat it as a learning and coordination tool. I would not recommend relying on it alone, handing it casually to young users, or using someone else’s activity as a substitute for personal research. Used within those limits, it offers a distinctive social layer that many ordinary finance apps do not provide.
Frequently Asked Questions
01What is FOMO and what can I use it for?
FOMO is an app designed to help users discover what is happening around them, including events, places, activities, and social opportunities. Its usefulness depends on the location and content available in your area. After installing it, you can typically browse recommendations, explore listings, and decide which experiences interest you before making plans or connecting with others.
02Is FOMO free to download and use?
FOMO may be free to download, but some features, events, services, or in-app options can require payment. Before confirming a purchase, check the pricing information shown inside the app and review whether subscriptions or one-time charges apply. Availability of paid features may also vary by country, platform, event organizer, or the specific version installed on your device.
03Does FOMO require my location or personal information?
FOMO may request access to your location so it can show relevant events, places, or recommendations nearby. It can also require account details such as an email address, phone number, or profile information, depending on the features you use. Review the app’s permission requests and privacy policy carefully, and only enable access that you consider necessary.
04Can I use FOMO without creating an account?
Some parts of FOMO may be available without registration, such as viewing general information or exploring selected content. However, features involving personalized recommendations, saving activities, contacting other users, booking, purchasing, or receiving notifications may require an account. The exact guest-access options can change, so check the current sign-up screen and app requirements after installation.
05Is FOMO available for both Android and iPhone?
FOMO’s availability depends on the particular app and the country associated with your device’s store. Before downloading, verify that the listing is published by the official developer and that your phone meets the required operating-system version. Also check recent reviews, update dates, and permissions, since features and availability can differ between Android and iOS versions.


